Strategic Insurance for Janitorial & Commercial Cleaning Companies

Insurance Built for the Crews You Send Out.
Every Night. Every Key. Every Contract.

Commercial cleaning companies carry risk most brokers never price — property in your care that isn't yours, crews driving their own cars between sites, a janitorial bond your biggest client demands, and workers' comp rates that punish the whole class. PFTN builds coverage around how a cleaning company actually operates, not a generic package renewed on autopilot.

Peoples First Tennessee logo
15+
Years of Strategic Advisory
500+
Organizations Served
100+
Carrier Relationships
98%
Client Retention Rate

Cleaning Companies Get Quoted, Not Advised

The Traditional Approach

The Commodity Trap

Most janitorial companies buy insurance the same way they lose contracts: fast, on price, and without anyone reading the fine print. A broker collects your payroll and revenue, sends it to three carriers, and hands you the cheapest quote. Nobody checks whether the policy excludes damage to the property you clean, whether your subcontractors are actually covered, or whether the certificate you send the property manager will survive a claim.

Then a crew member scratches a $40,000 terrazzo floor, a master key goes missing, or a client's contract demands a $2M umbrella and a janitorial bond you don't have — and the cheap policy turns out to be the most expensive thing you own.

The PFTN Approach

A Renewed Mindset

Our 4-Step Strategic Process starts months before your renewal by understanding how your company actually runs: how many buildings, what kind, who holds the keys, who drives, who's W-2 and who's 1099, and what every one of your contracts requires you to carry. Then we build a program that carriers compete for — because a cleaning company that can document its safety, screening, and key control is a risk underwriters want.

The result is coverage that actually responds, certificates that match contract requirements the first time, and a workers' comp strategy that drives your experience mod down year over year instead of just quoting it.

Coverage Built Around How Cleaning Companies Actually Operate

We don't sell policies. We build a program around the nine exposures that actually put a janitorial company out of business — and the three or four that most quotes quietly leave out.

General Liability

Premises, Operations & Completed Work

Slip-and-falls on a floor your crew just mopped, a wet-floor sign that wasn't placed, a chemical reaction that discolors a client's carpet. General liability is the foundation of a janitorial program — but only if the care-custody-control and lost-key exclusions are handled, not ignored.

Damage to Property in Your Care

Care, Custody & Control

Standard GL excludes damage to property you're working on or responsible for — which is everything you clean. We structure the endorsements and inland-marine solutions that respond when a buffer gouges a floor, a crew damages equipment, or a sealed surface gets ruined.

Janitorial Bonds & Employee Theft

Third-Party Fidelity & Crime

Clients ask for a "janitorial bond" because your people are alone in their building after hours. We place the third-party fidelity bonds and crime coverage that make you contract-ready — and explain why a bond is not the same thing as insurance.

Workers' Compensation

Rates, Mods & Return-to-Work

Janitorial class codes are rated for the worst operators in the industry. We pair competitive placement with the safety, screening, and return-to-work strategy that pulls your experience mod below 1.0 — the single biggest lever on your largest insurance cost.

Commercial Auto & Hired/Non-Owned

Crews Driving Between Sites

Your employees drive their own cars from building to building with your supplies in the trunk. That's your liability, not theirs. We build commercial auto, hired and non-owned, and fleet programs that match how your crews actually move — including the vans with your name on the side.

Lost Keys & Access Credentials

Key Control & Re-Keying Expense

A lost master key or badge can mean re-keying an entire office tower at your expense. We add lost-key coverage with limits that reflect the buildings you actually hold access to, and the key-control documentation underwriters want to see.

Umbrella & Contract Requirements

Certificates, Additional Insureds & Waivers

Property managers, hospitals, and national accounts write insurance requirements into every contract — $2M umbrellas, additional insured on a primary and non-contributory basis, waivers of subrogation. We structure the program so your certificates match the contract the first time, not after the claim.

Employment Practices Liability

Wage & Hour, Turnover & Subcontractors

High turnover, late-night shifts, and a mix of W-2 and 1099 labor make cleaning companies a frequent target for wage-and-hour and misclassification claims. EPLI with wage-and-hour defense protects the owners from the claims that come from inside the company.

Pollution & Chemical Exposure

Cleaning Agents, Disinfectants & Fumes

Mixed chemicals, improper ventilation, and disinfectant misuse are excluded under standard GL as "pollutants." Contractors pollution liability closes the gap for the claims a cleaning company is uniquely positioned to cause — and uniquely likely to be blamed for.

New here? Read the plain-English overview: Janitorial Insurance: What Commercial Cleaning Companies Need in 2026

Read the Guide →

Purchase with Purpose, Not Habit

The industry standard gives you 90 days to renew. That's not a strategy. We take a longer view, building a process that puts you ahead of the market and delivers coverage and cost outcomes most companies don't know are possible.

1

Strategic Discovery

We start by understanding your business goals, growth trajectory, and risk tolerance. Not just your current policy deck.

2

Risk Assessment

We identify current and future risks that could impact your success. We use a systematic, quantifiable approach to surface the risk issues most brokers never look for.

3

Solution Design

We build an integrated insurance and risk management strategy, not a one-size-fits-all policy package. Every solution is tailored to your risk profile, your industry, and your goals.

4

Ongoing Optimization

We monitor, adjust, and evolve your protection strategy. Your business changes, and your insurance should too. We continuously track your risk profile, claims trends, and market conditions.

From the first engagement with PFTN, we will educate, consult, and help you find strategic opportunities to impact your business. The shift starts with one conversation.

The Tools to Take Control

Most risk hides in plain sight. The PFTN platform puts a full suite of tools at your fingertips designed to illuminate what is otherwise overlooked. Training events, predictive modeling, compliance resources, risk assessment tools, and 24/7 access to everything you need to stay ahead of risk.

PFTN Torch

Shine a light on hidden risk through comprehensive assessments that uncover gaps in your coverage before they become costly surprises.

PFTN Benchmark

Project, track, and manage your experience modification rate with data-driven strategies that directly impact your workers’ compensation costs.

PFTN Advocate

Personal claims management by our dedicated claims manager, from first report through resolution, we advocate on your behalf.

PFTN Equip

Thought leadership workshops, lunch & learns, and executive briefings designed to keep your team ahead of emerging risks and industry trends.

PFTN Portal

Secure, 24/7 access to your full insurance program — desktop or mobile. Every document, every policy, always at your fingertips.

PFTN Vault

A private resource library built for your team — HR tools, compliance guides, and learning systems in one place.

The Future of Risk Placement

Most companies renew on autopilot, repeating the same process year after year and wondering why nothing improves. The truth is, the traditional approach to insurance wasn't designed to acknowledge growth or improving outcomes. It is designed to repeat the cycle with as little change or friction as possible at all points of the distribution channel.

The future of risk placement doesn't belong to companies that shop harder. It belongs to companies that stop renewing on autopilot and start doing the work between renewals that actually moves the needle. When a company commits to that kind of discipline, the market responds. Insurance stops being a cost you manage and starts becoming a position of strength.

These tools exist to help you get there. They're not a value add. They are the strategy.

Your Insurance Should Work as Hard as You Do

Here's what most insurance brokers won't tell you: the way commercial insurance is bought and sold is fundamentally broken. Brokers follow the same playbook: collect your data, send it to a few carriers, present the lowest quote, and move on. The process rewards speed and volume, not strategy and outcomes.

We built Peoples First Tennessee to be the opposite of that. Rather than selling insurance policies, PFTN is centered around finding and leveraging risk with a strategic process. With consultation, education, and proactive planning, our team partners with you to create a customized risk management strategy while easing the administrative burden of managing insurance.

  • Data-driven purchasing that challenges market assumptions
  • Streamlined administration that gives your team time back
  • Proactive risk management that prevents losses, not just pays for them
  • A relationship built on honest counsel, not sales quotas
"In over 15 years of working with hundreds of organizations, I've never sat down with a company that was already buying insurance strategically. But the few that break that cycle don't just save money — they transform their entire organization. Strategic insurance buying isn't just a cost decision. It's a cultural shift."
Ryan MeffordPresident, Risk Advisor

Meet the People Behind the Strategy

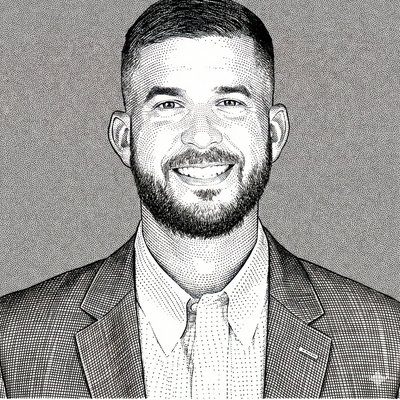
Ryan Mefford, President and Risk Advisor at Peoples First Tennessee

Ryan Mefford

President, Risk Advisor
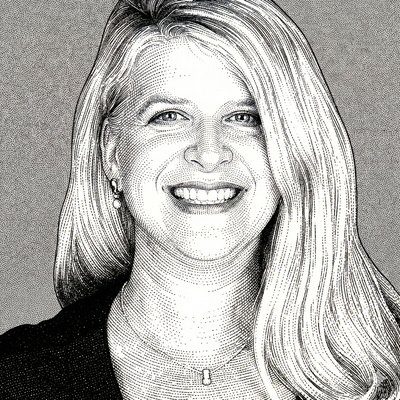
Lisa Fleenor, Director of Account Management

Lisa Fleenor

Director of Account Management
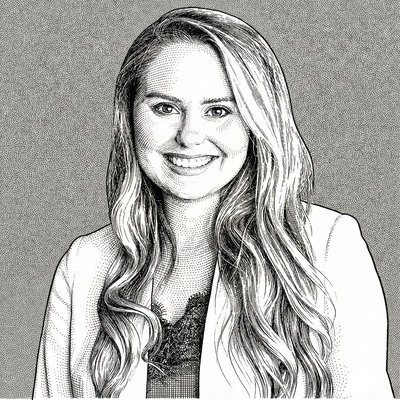
Rachel Talley, Director of Operations

Rachel Talley

Director of Operations
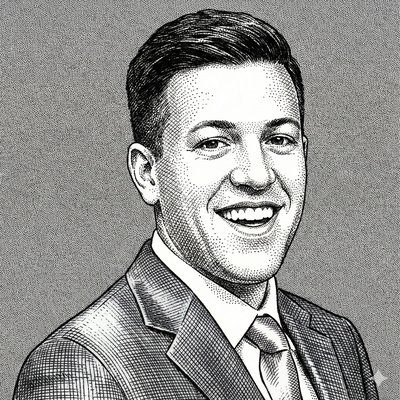
Chase Bristow, Risk Advisor

Chase Bristow

Risk Advisor
John Thomson, Risk Advisor

John Thomson

Risk Advisor
Zeke Plewniak, Business Development at Peoples First Tennessee

Zeke Plewniak

Business Development
Erin Boyd, Account Manager

Erin Boyd

Account Manager
Monica Mefford, Client Coordinator

Monica Mefford

Client Coordinator

Carrying the Light Forward

Tim Keller wrote that "to be the light means to illuminate what is true." These briefings exist to do exactly that — to shine a light on what the insurance industry would rather keep in the dark.

Bonds & Crime

The Janitorial Bond Your Biggest Client Will Ask For (and Why It Isn't Insurance)

Property managers require a janitorial bond because your people are alone in their building at night. But a bond protects the client, not you — and the surety can send you the bill. Here's what it covers, what it doesn't, and what to buy alongside it.

Read More →
General Liability

Care, Custody, and Control: The Exclusion That Turns a Scratched Floor Into an Uncovered Claim

A buffer gouges a terrazzo lobby. A stripper ruins a sealed floor. A crew knocks over a server rack. These are the claims cleaning companies actually have — and standard general liability excludes every one of them. Here's why, and how to fix it.

Read More →
Commercial Auto

Your Crew Drives Their Own Cars Between Buildings. That's Your Auto Claim.

Most cleaning companies don't own a fleet — crews drive their own cars from site to site with your supplies in the trunk. When one of them causes an accident, the client sues you, and the employee's personal policy may walk away. Hired and non-owned auto is the fix almost every janitorial quote leaves off.

Read More →

Janitorial Insurance Questions We Hear Every Week

What insurance does a janitorial or commercial cleaning company need?

At minimum: general liability, workers' compensation, and commercial auto (including hired and non-owned coverage for employees driving their own vehicles). Most commercial contracts also require a janitorial bond (third-party fidelity), an umbrella policy, and additional-insured status for the client. Companies that clean medical, industrial, or food facilities often need pollution liability as well. PFTN builds these as one coordinated program rather than separate quotes.

What is a janitorial bond, and is it the same as insurance?

No. A janitorial bond (also called a third-party fidelity bond or janitorial services bond) reimburses your client if one of your employees steals from their premises. It protects the client, not you, and the surety can seek repayment from your company. Insurance protects your business directly. Most commercial cleaning contracts require both a bond and liability insurance.

Does general liability cover damage to a client's floor or property while we clean it?

Usually not by default. Standard general liability policies exclude damage to property in your care, custody, or control — which is exactly the property a cleaning crew works on. Covering a damaged floor, countertop, or piece of equipment requires specific endorsements or a separate installation/property-in-care solution. This is the most common uncovered claim we see on janitorial accounts.

How much does janitorial insurance cost?

It depends on payroll, revenue, the types of buildings you clean, your claims history, and what your contracts require. Workers' compensation is typically the largest line because janitorial class codes carry higher base rates. The biggest cost driver you control is your experience modification factor — a cleaning company with a mod of 0.85 pays roughly 30% less than a competitor at 1.20 on the same payroll.

Do we need workers' comp for subcontractors or 1099 cleaners in Tennessee?

If a subcontractor does not carry their own workers' compensation, you can be held responsible for their injuries, and your carrier will charge you premium for their payroll at audit. Tennessee requires workers' comp for most employers with five or more employees, and misclassifying employees as 1099 contractors creates both a workers' comp and a wage-and-hour exposure. Collect certificates from every sub, every year.

Our employees drive their own cars between job sites. Are we covered?

Not by their personal auto policies — most personal policies exclude business use, and the client will sue your company anyway. Hired and non-owned auto liability covers your business when an employee has an accident driving their own vehicle for work. It is inexpensive and routinely left off janitorial quotes.

Work That Matters. Purpose That Lasts.

At Peoples First Tennessee, we believe your work is more than a job. It's a calling. We're building a team of people who see insurance not as a transaction, but as a way to serve others with excellence and integrity.

Human Dignity

Every person we serve, every client, every colleague, carries inherent worth. We don't treat people as policy numbers. We approach every relationship with the conviction that protecting someone's livelihood is a deeply human act, and that the work we do has real meaning in the lives of others.

Personal Calling

We believe the best work happens when people bring their full selves to what they do. At PFTN, your role isn't just a function. It's an opportunity to use your unique gifts in service of something bigger. We hire people who are driven not by quotas, but by the belief that their work can genuinely impact the businesses and families we protect.

Culture of Excellence

Culture becomes meaningless the moment it becomes marketing. Real culture isn't a brand statement or a tool for public recognition. It's the quiet measure of whether what you say you'll do in public is actually what gets done in private. It's dignity extended when no one's watching. Grace given when it costs you something. Excellence held to when no client will ever see it. That's the standard here, held together by people humble enough to know they need the same grace they give.

"Work is not primarily a thing one does to live, but the thing one lives to do. It is the full expression of the worker's gifts, the thing that gives you a sense of purpose and calling."

Timothy Keller, Every Good Endeavor

What to Expect at PFTN

The values above aren't aspirational. They're how we operate every day. We're a tight-knit team in Knoxville serving clients all over the U.S., where people are trusted with real responsibility, encouraged to grow, and reminded that the work we do has real meaning in the lives of others.

We don't think purpose is something you have to chase outside of work. We think the right environment calls you to purpose in a manner that harnesses your gifts and talents and can be a catalyst for joy. If that sounds like what you've been missing, reach out.

Investing in the Whole Person

We invest in the whole person — not just the employee. That means caring for your financial future with a max-match 401(k) and annual financial literacy classes. Supporting your well-being through paid counseling services and gym memberships. And honoring your desire to serve others with 40 hours of paid community service every year.

These aren't perks designed to recruit. They're commitments designed to help you flourish — spiritually, financially, physically, and personally.

Join Our Team →

Stop Buying Cleaning Insurance by the Quote.

Bring us your current policies and your three biggest contracts. We'll show you, line by line, where the coverage matches what you've promised your clients — and where it doesn't.